Marinade Q3 2026 quarterly report
Stake grew 21% to 7.94M SOL, led by Native and institutional staking, and revenue rose a quarter on the stake auction. The auction cleared above the network benchmark in 48 of 51 epochs.
July 1 to September 30, 2026 · Solana epochs 996–1046 · all figures as of September 30, 2026.
| Headline | Value | Change |
|---|---|---|
| SOL staked, end of Q3 | 7.94M SOL | +21.2% QoQ |
| Revenue, Q3 | $1.00M | +25.9% QoQ |
| Protected Staking Rewards (PSR) paid by bonds | 97.5% | of 77.0 SOL paid to stakers |
| Auction yield vs benchmark, before Marinade's fee | +0.26% | ahead in 48 of 51 epochs |
| Institutional stake (Select) | 1.68M SOL | +38.7% QoQ |
New to Marinade? What the protocol does, in four lines
- The products. Marinade helps retail users, DAOs and institutions manage and optimize their staked SOL. mSOL is a token you hold and trade while the SOL behind it stays staked; Native stakes from your own wallet without giving up custody; Select serves institutions, ETFs and clients of qualified custodians; Customized Rewards pays rewards in a token of your choice.
- The auction. Validators bid for Marinade's stake in the Stake Auction Marketplace (SAM), backing each bid with collateral called a bond. Their bids raise what stakers earn; Marinade keeps a share as revenue.
- The benchmark. The Solana Staking Index (SSI) measures what plain, neutral staking on Solana pays. It is the yardstick used throughout.
- The token. MNDE is the governance token of the Marinade DAO, which owns the protocol; proposals are called MIPs and are voted on-chain.
The quarter in five lines
- Growth came from Native and Select. Together they added 1.68M SOL; Select now carries more than a fifth of the book.
- Revenue rose on the auction. Validator bond settlements grew 38% in SOL. Marinade's fee now targets a minimum SOL revenue each epoch, and shorter epochs gave the quarter 51 auctions against 46. With SOL higher, revenue rose 26% in dollars.
- The auction cleared above the benchmark in 48 of 51 epochs, 5.93% against the index's 5.67%, before Marinade's fee; stakers earned below the index after it.
- MIP-22 went live. Buybacks bought 4.2M MNDE on the open market from July, and the first distribution to voting stakers opened on October 1.
- Shipped. The audited mSOL contract upgrade, no 0.2% delayed-unstake fee on native products, Explore, and full validator coverage of downtime under MIP-23.
Letter from the core contributor
Q3 was good for the numbers and humbling for how we work. Stake grew 21% to 7.94M SOL and revenue passed a million dollars. Part of that was our work. A fair share came from a rising SOL price and shorter epochs. Sometimes we get lucky, and I would rather say so.
At the start of the year we said 2026 would be about three words: earn, borrow and spend. The idea under them holds. People buy good assets to grow their wealth, then sell them to pay for life. We want you to spend against what you hold and let the yield pay it back over time. We call it buy now, pay never. Solana is where it starts.
Staking alone will not carry that. Yield is less elastic than we once hoped. Nobody moves for an extra half point on an asset that can drop ten percent in a day, and staking margins keep compressing across the industry. This year we also stopped treating institutional staking as our main card. Select keeps growing and the ETF runs through it. Our future sits closer to the people who hold serious SOL in their own wallets and want it working without selling a coin.
Every quarter we ask the team what gets in the way. The answer at the top of the list this time was blunt: we ship at 80 percent and move on. Borrow is the clearest case. It went live in beta in July and works well. We barely told anyone, and the first version asked people to post collateral and take a loan in a single flow. That design was my mistake. Confused people never buy. The yield Rock taught a similar lesson. The auction margin stayed positive on average but varied through the quarter, moving mostly with code and network changes, while the validator conversations we planned around it never really happened. The team also said we have the best yield and do a poor job of showing it, and that our customer still means different things to different people here.
So Q4 has one Rock. Smart accounts go into production, and at least 100 users earn continuous APY through them. Close to half the team is on it. The first version is small on purpose. You deposit into a Kamino market, rewards accrue continuously, you can withdraw any time, and you can borrow against that deposit. Strategies built on mSOL come after that. So does the card, which needs this layer underneath and which we will not rush. Breakpoint is the target for the first piece people can touch. Audits come first.
Most of the smaller work this quarter goes to finishing what is already in flight, including staking history in the app and the rebuilt Instant Unstake. By the end of each quarter a Rock is either done or not done, and we owe it to the team to say which. Stubborn on the vision, flexible on the details. Standing still is usually the riskier choice.
One more thing from September. On the 25th two malicious governance proposals were submitted through a flaw in the DAO's voting program. The council vetoed both within about six hours, no funds moved, and a fix went out the same night. More safeguards are on the way.
repe, core contributor
Native and Select grew, mSOL eased
Native grew by almost half and Select by more than a third, while mSOL and Customized Rewards declined. In dollars the rise is steeper, +92.3% to $945.5M, because SOL rose 58.8% over the quarter. Select's share of Marinade's total stake rose from 18.5% to 21.2%.
| SOL staked | Q4 2025 | Q1 2026 | Q2 2026 | Q3 2026 | QoQ |
|---|---|---|---|---|---|
| Total | 9,359,013 | 6,862,729 | 6,552,849 | 7,939,130 | +21.2% |
| Liquid (mSOL) | 3,444,359 | 2,813,440 | 2,437,004 | 2,272,275 | −6.8% |
| Native | 3,128,243 | 2,853,413 | 2,559,372 | 3,769,931 | +47.3% |
| Select (institutional) | 2,747,669 | 917,145 | 1,213,840 | 1,683,339 | +38.7% |
| Customized Rewards | 0 | 258,876 | 305,009 | 192,161 | −37.0% |
Source: Marinade API (tlv/history), end-of-quarter snapshots. The mSOL row is net of pending unstake tickets (14,858 SOL at September 30); adding those and the instant-unstake liquidity pool (6,565 SOL) reconciles the rows to the total.
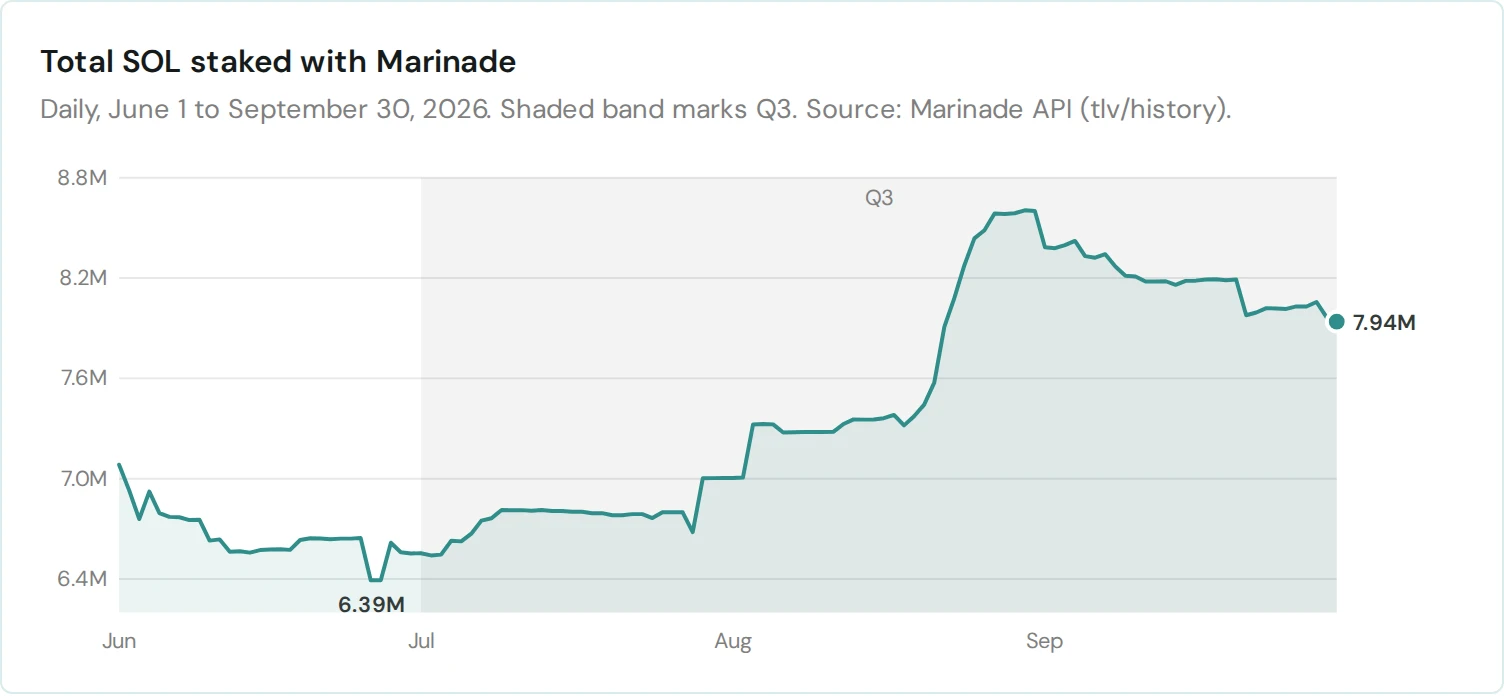
Most of the growth arrived in August, and part of it reversed in September. Across the category, stake in Solana stake pools rose about 1% between epochs 995 and 1046 while total network stake grew 3.1%, so the pooled share of all staked SOL slipped from about 27% to 26.6%.
Most of Native's growth arrived between August 19 and 27. Select's validator set grew from 24 to 65 in July and stood at 64 at quarter end.
Revenue rose a quarter on the auction
Revenue was 10,918 SOL, 10.3% above Q2, and $1,001,410 in dollars, a quarter above. Validator bond settlements drove the growth. mSOL unstake fees fell by more than three quarters, and Native delayed-unstake fees nearly stopped once the 0.2% fee on native products was removed on July 6.
Two changes raised settlements. Since June 22, Marinade has set its fee each epoch to collect at least 200 SOL, within a 2–16% fee range, so the DAO kept a larger share of what validators bid. And shorter epochs gave the quarter 51 auctions against Q2's 46. Average SAM stake was flat, and gross bid charges, what validators paid into the auction, rose 10.6% in SOL. The higher SOL price added to the dollar figure, most of all in September, the quarter's largest month. mSOL unstake fees fell back from June, when mSOL exits had been unusually high. Revenue is stated before the 10% of auction fees that funds MIP-22 buybacks.
| Revenue | Q2 2026 | Q3 2026 | QoQ |
|---|---|---|---|
| Revenue (USD) | $795,154 | $1,001,410 | +25.9% |
| Revenue (SOL) | 9,897 SOL | 10,918 SOL | +10.3% |
| Validator bond settlements (SAM and Select fees) | 7,611 SOL | 10,510 SOL | +38.1% |
| mSOL unstake fees | 1,785 SOL | 401 SOL | −77.5% |
| Native delayed-unstake fees | 501 SOL | 7 SOL | −98.6% |
| What moved it | |||
| Average stake over the quarter | 7.01M SOL | 7.53M SOL | +7.5% |
| Average SOL price | $80.58 | $89.35 | +10.9% |
| SAM bid charges, gross (on-chain) | 9,964 SOL | 11,020 SOL | +10.6% |
| Staker protection (PSR) | |||
| Cover paid to stakers (downtime, commission increases) | 337.2 SOL | 77.0 SOL | −77.2% |
| of which paid by validators' bonds | 85.5% | 97.5% | +12.0 pts |
Protected Staking Rewards made stakers whole for 42 downtime and commission-increase events across 22 validators. Since MIP-23 took effect at epoch 1040, validators' bonds cover all downtime on auction stake, so the validator that caused a shortfall bears its cost.
Governance decides where revenue goes. Since July, 10% of auction fees buys MNDE for MNDE stakers under MIP-22, and the rest of the revenue accrues to the DAO.
The auction beat the benchmark, stakers earned below it
Marinade's auction cleared above the Solana Staking Index in 48 of the quarter's 51 epochs, averaging 5.93% against the index's 5.67%. That is the auction's yield before Marinade's own fee. Stakers earn that yield minus the fee, and since June 22 the fee has targeted a minimum SOL revenue instead of holding stakers at the index. Native stakers earned 5.32% against the index's 5.84%, 0.51 points below it and below it in every epoch. These two figures use the APY API's own basis, which compounds per epoch and puts the index about 0.2 points higher. mSOL holders earned about 5.4%, measured from the mSOL price.
The margin widened through July and August, peaking in early September, then fell away in the quarter's last week. The auction cleared about 0.2 points below the index in epochs 1041 and 1042, only marginally above it in 1045 and just below it in 1046. Both the auction's yield and the index were lower than in Q2, in line with Solana's falling issuance. Making the margin durable takes more validators bidding with more collateral behind them.
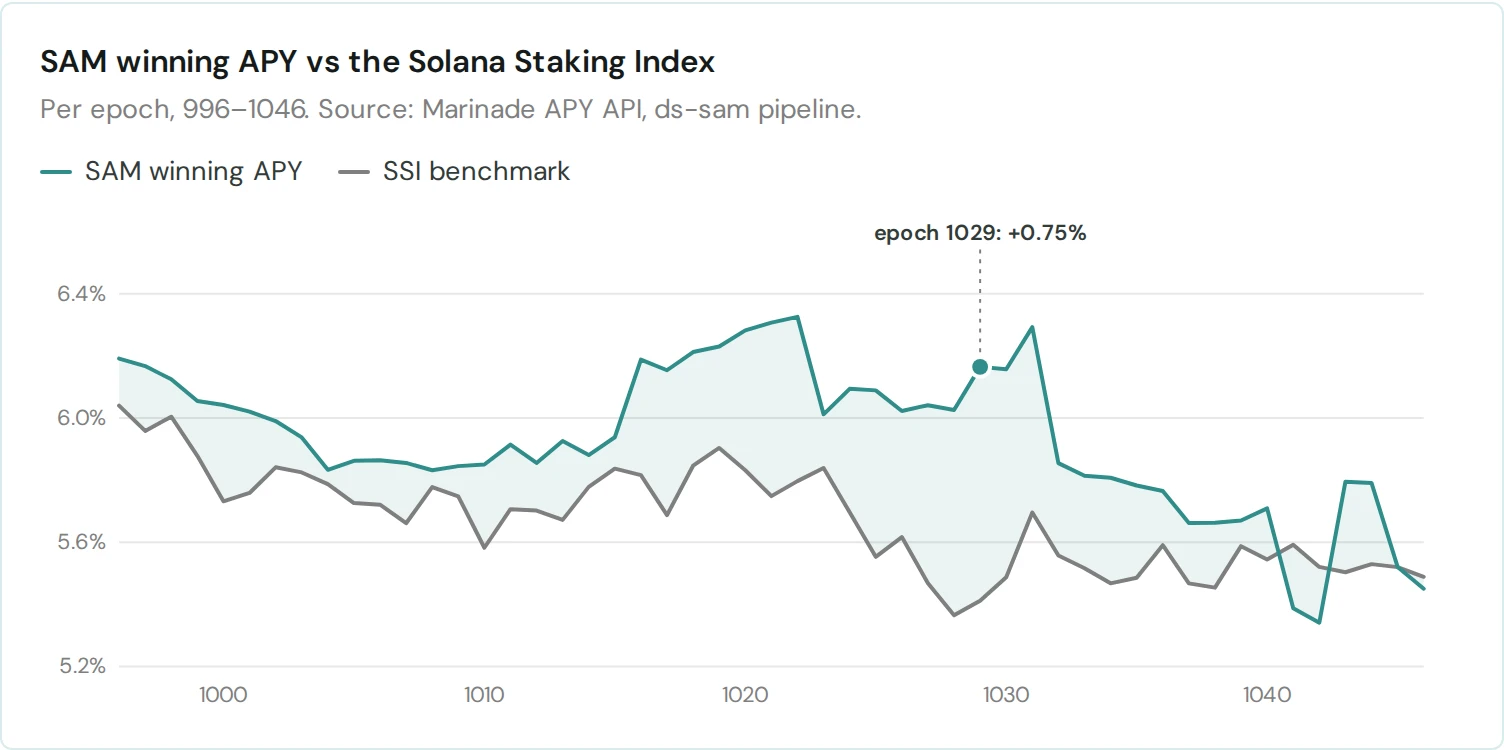
The index measures neutral staking: inflation plus block rewards, maximal extractable value (MEV) excluded. The auction's clearing yield is measured before Marinade's fee, and part of the spread is structural, since SAM captures MEV that the index excludes by construction. Both series are annualized on each epoch's measured duration, the basis Marinade uses internally. Solana cut slot times to 350 ms and then 300 ms in August, and to 250 ms in September, which shortened epochs from about two days to about a day and a third.
MNDE, governance and the treasury
MIP-22 took effect in July. Since then, 10% of auction fees has gone to open-market MNDE buys. Over the quarter 906.6 SOL bought 4.20M MNDE, held in the buyback wallet until the first distribution on October 1. On July 7 the DAO moved its existing Orca MNDE/mSOL position (10.96M MNDE) into a new 10M MNDE position in the 0.3% pool that MIP-22 names.
| MNDE snapshot (Sep 30) | Value |
|---|---|
| Price | $0.0261 (+39.0% QoQ) |
| Total supply (on-chain) | 700.0M |
| Circulating, measured (total minus DAO reserve) | 510.3M |
| Implied market cap at measured circulating | ≈$13.3M |
| MNDE staked in governance | 103.71M |
| MNDE staking accounts | 15,157 |
For MNDE holders: how the MIP-22 revenue share works
- Stake and vote. Eligible wallets have MNDE staked in Marinade's governance and have voted on at least one community proposal in the twelve months up to the end of the quarter. One vote is enough; council votes do not count.
- What you receive. MNDE bought on the open market with 10% of auction fees, shared pro rata to each wallet's average voting weight (veMNDE) over the quarter. Once eligible, the whole quarter's balance counts, including days before the vote.
- How to claim. Each quarter's distribution opens after the quarter ends and stays claimable for six months at app.marinade.finance/campaign. Claimed MNDE can be restaked.
MIP-23, approved in September, moved downtime cover for auction stake entirely onto validators' bonds. Previously bonds covered the first half of a downtime shortfall and the DAO reserve the rest, which came into play only in severe outages. Bond requirements did not change.
On September 25 an attacker used a bug in the DAO's voting program to give a small MNDE position far more voting weight than it should have had, and opened two malicious proposals: one reused the "MIP-23" name to replace the voting program, the other would have moved the DAO treasury. Both were being voted down when the council vetoed them, within about six hours. A configuration fix went in the same night, no funds moved, and mSOL, Native, SAM and staked SOL were not affected. The maintainers of the governance software have been notified.
The DAO's balance sheet is on-chain and readable in any explorer. At September 30 its reserve, council and operations accounts held 303.8M MNDE, $7.91M at that day's price, against roughly $115K of non-MNDE liquid assets. A further 44.9M MNDE sat in other accounts funded by the DAO: the pool position, the buyback wallet and a wallet funded from the operations wallet and staked in governance. Most of the treasury is held in MNDE, so its realizable value depends on market depth as well as on the quoted price.
Account-level balances (on-chain, September 30)
| Account | Role | Holdings | USD (spot) |
|---|---|---|---|
| B56RWQGf…25YtvG | DAO reserve treasury (Realms; held since inception, non-circulating) | 189,716,233 MNDE | $4.94M |
| J5BEceL5…FfCzhs | Council budget vault (Realms; funds DAO-authorized spending) | 113,104,161 MNDE | $2.95M |
| 89Srbjbu…CeArBgB | DAO operations wallet | 1,005,239 MNDE + 650 mSOL + 456 USDC | $0.03M + $0.11M |
| Orca MNDE/mSOL position | Protocol-owned liquidity (MIP-22), held by the operations wallet; MNDE-only and out of range at current prices | 10,000,000 MNDE | $0.26M |
| BBaQsiRo…fsJ6x | Buyback wallet (MIP-22 accumulation, distributed after quarter end) | 4,199,948 MNDE | $0.11M |
| CMbdJVZx…2FkP7 | Wallet funded from the operations wallet, MNDE staked in governance | 30,654,345 MNDE | $0.80M |
Balances read on-chain as of September 30, 2026, valued at that day's prices (SOL $119.09, MNDE $0.0261). After the quarter: the first MIP-22 distribution opened on October 1, 2026: 4.24M MNDE to 43 eligible wallets, claimable until April 1, 2027. The same day, 4.09M MNDE left unclaimed in two earlier reward rounds was returned to the council budget vault.
Shipped in Q3
The quarter delivered the mSOL contract upgrade promised in Q2, removed the 0.2% fee to leave native staking, and opened the validator data behind Marinade's stake decisions to everyone.
| Date | Release | What it does |
|---|---|---|
| Jul 6 | No 0.2% delayed-unstake fee on native products | Native, Select and Customized Rewards stakers leave without the 0.2% fee (a flat 0.003 SOL charge remains); mSOL keeps its 0.2% |
| Jul 8 – Aug 6 | Marinade Borrow | Borrow against staked SOL from the Marinade app; USDC borrowing added in late July, open to all users Aug 6 |
| Jul 14 | Portfolio page update | Performance chart by default, mSOL counted in wallet balance, send and receive any SPL token |
| Jul 16 | mSOL contract upgrade live | Neodyme-audited upgrade of the liquid staking program, including improved handling of delinquent stake |
| Aug 6 – 27 | Explore | A page for every Solana validator: take rate and incident record per epoch |
| Sep 2 | SAM bid simulator | Validators model a bid against a recent auction before placing it |
| Sep 15 | Continuous rewards indexing | Staking rewards reports are built as rewards are indexed, instead of in periodic batches |
| Sep 21 | MIP-23 applied | Validators' bonds cover the full downtime band for auction stake, for every epoch from 1040 |
On August 12 a hosting provider's routing fault took 28.8% of Solana's stake offline, close to the threshold at which the network stops finalizing; under 1% of Marinade's stake sat on the affected validators. Marinade published an analysis of the event.
Where Marinade stands
Measured on-chain at epoch 1046, the epoch spanning quarter end, Marinade's pools held 7.85M SOL of delegated stake, up 21.0% over the quarter. Among commercial staking products that keeps Marinade third, behind Jito (10.3M, including directed stake) and Binance (10.2M), and ahead of Jupiter (5.2M) and Drift (2.8M). Delegated stake is measured at an epoch rather than at quarter end, so it differs slightly from the 7.94M total above.
Over the same epochs Jito grew 4.2%, Binance 2.0%, Jupiter fell 3.2% and Drift rose 0.9%. No peer has published Q3 results yet, so this report does not compare revenue.
Institutional staking kept growing. The Select set expanded to 64 identity-verified validators, the Canary Marinade Solana ETF (Nasdaq: SOLC) stakes through Marinade Select, and, since April, allocators can stake through Marinade from Anchorage Digital's federally chartered custody.
Ranking covers commercial staking products and is measured as delegated stake at an epoch. Three larger pools are excluded as delegation programs rather than products: the Solana Foundation's (26.5M SOL), the Firedancer client-adoption program (8.0M), and one unattributed 24.1M pool spread across six validators. Jito's figure includes stake directed through Jito to specific validators, the same basis as in the Q2 report; its pool alone held 9.7M SOL, which would place Binance second. Sanctum runs many separate pools, one per liquid staking token, rather than one staking operation and is not comparable on this basis.
Data: Trillium.
Priorities for Q4
- Smart accounts in production (the Q4 Rock). At least 100 users earning continuous APY through a Marinade smart account: deposit into a Kamino market, rewards accrue continuously, withdraw any time, and borrow against the deposit. The first piece people can use is targeted for Breakpoint, after audits.
- Instant Unstake, rebuilt. Take the new instant-unstake contract through its audit and into the app.
- Staking history in the app. A full log of staking and unstaking activity for every account.
- The second MIP-22 distribution. Buybacks continue at 10% of auction fees, with the next distribution after December 31.